State Lines and Inheritance: The Hidden Tax Obligations That Could Shrink Your Windfall
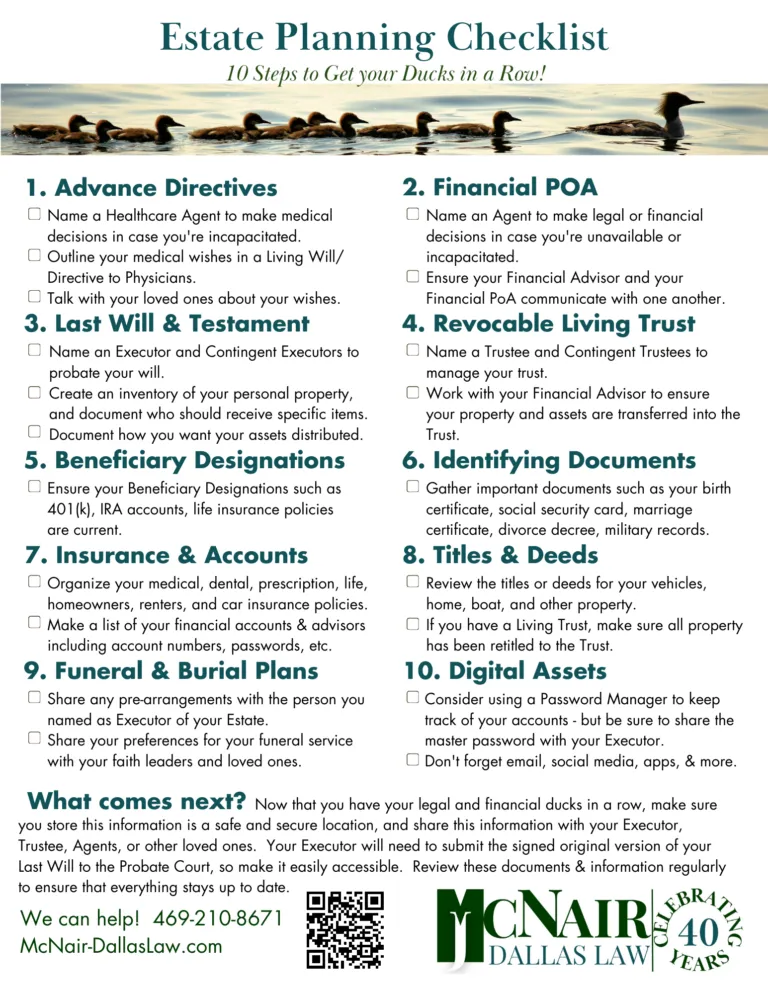
Photo: estate planning documents inheritance paperwork family meeting attorney, via mcnair-dallaslaw.com
Receiving an inheritance is rarely a straightforward experience. Beyond the emotional weight that accompanies a loved one's passing, beneficiaries frequently discover that the financial picture is more complicated than they anticipated. One of the most common — and costly — surprises involves state-level taxes that apply to inherited assets. At RyanTax Pro, we work with clients across the country who arrive at our door after the fact, already facing bills they did not see coming. This guide is designed to help you understand the landscape before that happens.
Federal vs. State: Two Entirely Different Conversations
The federal government does not impose an inheritance tax. What it does impose is an estate tax, but that applies to the estate itself — not to the individual beneficiary — and only when the gross estate exceeds $13.61 million as of 2024. For most American families, the federal estate tax simply does not apply.
State taxes are a different matter entirely. There are two distinct types to understand:
Estate taxes are levied against the total value of a deceased person's estate before assets are distributed. The estate pays this tax, which can reduce what beneficiaries ultimately receive.
Inheritance taxes are levied against the beneficiary directly, based on the value of what they receive. These are rarer, but they place the obligation squarely on the person inheriting — not on the estate.
Some states impose one, some impose both, and the majority impose neither. Knowing which category applies to your situation is the essential first step.
Which States Have These Taxes?
As of 2024, twelve states and the District of Columbia impose a state-level estate tax: Connecticut, Hawaii, Illinois, Maine, Maryland, Massachusetts, Minnesota, New York, Oregon, Rhode Island, Vermont, and Washington. Exemption thresholds vary considerably. Massachusetts and Oregon, for example, begin taxing estates valued above just $1 million — a threshold that is not difficult to reach when real estate is factored in.
Six states impose an inheritance tax: Iowa (being phased out), Kentucky, Maryland, Nebraska, New Jersey, and Pennsylvania. Maryland is notable for imposing both an estate tax and an inheritance tax, making it one of the more challenging states for beneficiaries.
Inheritance tax rates and exemptions typically vary based on your relationship to the deceased. Spouses are almost universally exempt. Direct descendants — children and grandchildren — often receive favorable treatment or full exemptions. More distant relatives and unrelated beneficiaries typically face the highest rates, sometimes exceeding fifteen percent.
How to Calculate Your Potential Liability
If you are a beneficiary in one of the states listed above, your first task is to identify which state's laws apply. Generally, the relevant state is where the deceased person was domiciled at the time of death — not necessarily where you live as the beneficiary. However, real property located in a taxable state is typically subject to that state's rules regardless of where the deceased resided.
From there, the calculation involves:
- Identifying the gross value of the estate or the portion you are inheriting. This includes cash, investments, real estate, retirement accounts (with important caveats), business interests, and personal property.
- Applying the applicable exemption. Many states exempt amounts below a specified threshold from taxation entirely.
- Determining your relationship to the deceased. This affects both the exemption amount and the applicable tax rate.
- Calculating the marginal tax owed. State estate and inheritance taxes are generally progressive, meaning higher values are taxed at higher rates.
Because these calculations involve multiple variables, working with a tax professional who has experience in the relevant state's rules is strongly advisable. At RyanTax Pro, we frequently assist clients in modeling these scenarios before assets are formally transferred.
Strategic Planning Moves Beneficiaries Should Consider
Many people assume that once a loved one has passed, there is little a beneficiary can do to influence their tax outcome. That assumption is not always correct. Several legitimate planning strategies can reduce or defer state tax obligations.
Disclaim the inheritance strategically. Federal and state law allows beneficiaries to formally disclaim, or refuse, all or part of an inheritance within nine months of the decedent's death. This causes the assets to pass to the next named beneficiary, which may be someone in a lower tax bracket or in a state with no inheritance tax. This approach requires careful coordination with an estate attorney and a tax advisor.
Understand how retirement accounts are treated. Inherited IRAs and 401(k) accounts are subject to their own set of rules under the SECURE Act and its successor legislation. While these accounts are generally included in the estate for estate tax purposes, distributions are taxed as ordinary income to the beneficiary. Coordinating the timing of those distributions with your overall income picture can reduce the total tax impact.
Consider the stepped-up basis on appreciated assets. When you inherit appreciated property — a home that has grown significantly in value, for example — you typically receive a stepped-up cost basis equal to the fair market value at the date of death. This means that if you sell the property shortly after inheriting it, you may owe little or no capital gains tax at the federal level. This is a significant advantage that beneficiaries should not overlook.
Evaluate residency implications. If the decedent maintained residency in multiple states, there may be a question about which state has taxing authority over the estate. These disputes can be complex and expensive, but they are not uncommon — particularly for individuals who owned property in multiple states or who relocated late in life.
The Timing Factor
One detail that surprises many beneficiaries is that state estate and inheritance taxes can be due relatively quickly after a person's death — sometimes within nine months, mirroring the federal estate tax timeline. If the estate includes illiquid assets such as real estate or a family business, generating the cash to pay that tax can create significant pressure. Executors and beneficiaries alike benefit from understanding these deadlines before they arrive.
A Note on Planning Before the Fact
While this article focuses on beneficiaries, it is worth acknowledging that the most effective tax planning happens before death, not after. If you are in the process of estate planning — or if you have a family member who is — working with a tax professional to structure the estate in a way that minimizes state-level exposure is time well spent. Strategies such as irrevocable trusts, annual gifting programs, and charitable vehicles can all reduce the taxable estate and protect more assets for the people you intend to benefit.
At RyanTax Pro, we believe that smart tax planning is not just about what you file — it is about understanding the full financial picture at every stage of life, including the transitions that are hardest to anticipate. If you have recently received or expect to receive an inheritance, we encourage you to reach out for a personalized consultation before making any final decisions about how to handle the assets involved.