Untangling Your Finances: The Tax Consequences of Divorce Most People Learn Too Late
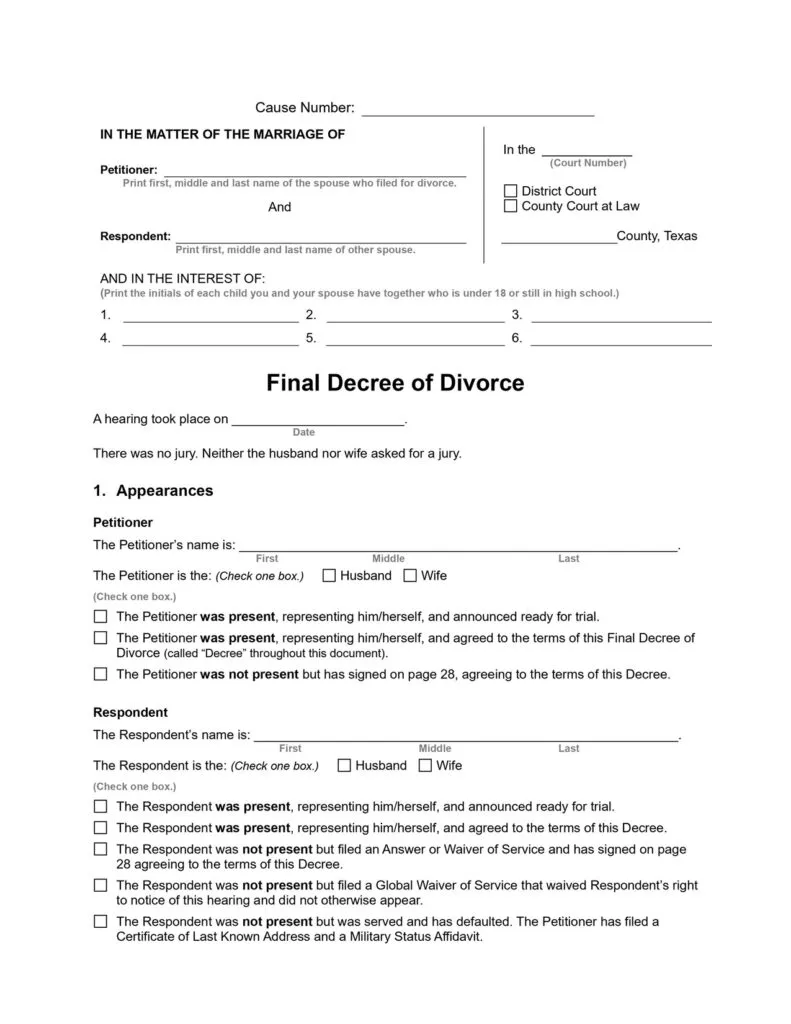
Photo: divorce financial documents tax forms couple separation, via onlinedivorcetexas.com
Divorce is, at its core, a legal and financial reorganization. Courts divide property, establish support arrangements, and reassign parental responsibilities — all with binding consequences. What the court documents rarely explain, however, is how each of those decisions intersects with the federal tax code. By the time many individuals discover the tax cost of an agreement they already signed, the opportunity to negotiate a better outcome has long passed.
This guide is intended to change that. Whether you are in the early stages of separation or finalizing a settlement, understanding the tax dimensions of divorce is essential to protecting your financial future.
Filing Status: The First Decision That Matters
Your marital status on December 31 of the tax year determines your filing status for that entire year. This is a rule that surprises many people going through separation. If your divorce is not legally finalized by December 31, you are still considered married in the eyes of the IRS — and you must file either as Married Filing Jointly or Married Filing Separately.
Married Filing Jointly typically yields the most favorable tax outcome for couples, offering wider brackets and access to credits that phase out under Married Filing Separately rules. However, filing jointly when a marriage is dissolving requires both parties to sign the return and agree to share responsibility for any errors, omissions, or subsequent audits. For spouses who no longer trust each other's financial disclosures, this shared liability can be a serious concern.
Married Filing Separately protects each spouse from the other's tax obligations, but it comes at a cost. Several deductions and credits — including the student loan interest deduction, the earned income tax credit, and certain education credits — are unavailable to taxpayers who use this status. The decision requires careful analysis of both spouses' income and deduction profiles.
If you have a qualifying dependent child and meet certain residency requirements, you may qualify for Head of Household status in the year your divorce is finalized or in subsequent years. This status offers a larger standard deduction and more favorable bracket structure than filing as Single, and it can represent a meaningful tax advantage for the custodial parent.
The Dependent Claim: A Source of Significant Conflict
For divorcing parents, the question of who claims the children as dependents is often contentious — and financially significant. The child tax credit, currently worth up to $2,000 per qualifying child, along with the dependent care credit and certain education-related benefits, flows to the parent who claims the child.
The IRS default rule awards the dependency exemption to the custodial parent — defined as the parent with whom the child spends the majority of nights during the year. However, this right can be transferred to the non-custodial parent through a signed Form 8332, which the custodial parent must execute and the non-custodial parent must attach to their return.
Divorce agreements frequently address dependent claims, sometimes alternating the designation between parents in odd and even years. What these agreements sometimes fail to account for is that certain tax benefits — including Head of Household filing status and the earned income tax credit — cannot be transferred via Form 8332. They are tied to physical custody regardless of what the divorce decree specifies.
A parent who believes they are entitled to certain credits based on a divorce agreement may be surprised to learn that the IRS does not recognize that agreement as controlling when the statutory rules conflict with it.
Alimony: A Fundamentally Changed Landscape
Prior to 2019, alimony payments were deductible by the paying spouse and reportable as income by the receiving spouse. This arrangement allowed couples to structure support payments in a tax-efficient manner, with the higher-earning spouse receiving a deduction while the lower-earning recipient — often in a lower bracket — paid tax at a reduced rate.
The Tax Cuts and Jobs Act of 2017 eliminated this treatment for divorce agreements executed after December 31, 2018. For any divorce finalized on or after January 1, 2019, alimony is neither deductible by the payer nor includable in the recipient's income. The paying spouse receives no tax benefit, and the receiving spouse pays no tax on the support received.
This change has meaningful implications for how support amounts are negotiated. Under the old regime, a $3,000 monthly alimony payment effectively cost the payer less than $3,000 after the deduction. Under current law, the payer receives no offset. Attorneys and financial advisors who are not current on this change — or who are working from older templates — may inadvertently structure agreements that no longer reflect the true after-tax cost to each party.
Divorce agreements predating 2019 that have not been modified retain the old tax treatment, provided the modification does not specifically adopt the new rules. Individuals renegotiating older agreements should be aware that certain modifications can inadvertently trigger the new, less favorable treatment.
Asset Division: Where Hidden Tax Costs Reside
Dividing marital assets may appear straightforward on a balance sheet, but the tax basis of those assets — what was originally paid for them — determines the actual after-tax value each spouse receives.
Consider two assets of equal current market value: a savings account with $150,000 in cash, and a brokerage account holding $150,000 in stock purchased years ago for $50,000. On paper, both are worth the same. In practice, the spouse who receives the brokerage account inherits an embedded capital gains liability of approximately $100,000, which will be taxed when the shares are eventually sold. Depending on the applicable rate, that could represent $15,000 to $20,000 in future taxes — a cost that does not appear anywhere in the asset division summary.
Retirement accounts present similar complexity. A 401(k) or traditional IRA contains pre-tax dollars that will be fully taxed upon withdrawal. A Roth IRA, by contrast, holds after-tax contributions and grows tax-free. Treating these accounts as equivalent in a divorce settlement without adjusting for their different tax treatments can result in one spouse receiving substantially less value than the nominal figures suggest.
Transferring retirement assets in a divorce requires a Qualified Domestic Relations Order (QDRO) for employer-sponsored plans. Without this document, a transfer that would otherwise be tax-free becomes a taxable distribution subject to income tax and potential early withdrawal penalties.
Common Mistakes and Strategic Opportunities
Several errors appear with particular frequency in divorce-related tax situations:
-
Failing to update withholding. A newly single taxpayer's income and deduction profile is entirely different from when they were married. Without updating Form W-4 with an employer, underwithholding — and an unexpected tax bill — is a common outcome.
-
Overlooking the home sale exclusion. A married couple can exclude up to $500,000 in capital gains on the sale of a primary residence. A single filer's exclusion is $250,000. Selling the marital home before the divorce is finalized may preserve access to the larger exclusion, depending on timing and residency requirements.
-
Missing innocent spouse relief. If a joint return contained errors attributable to one spouse's actions, the other spouse may qualify for relief from the resulting tax liability. This option is time-sensitive and requires a formal IRS application.
-
Neglecting estimated tax payments. Spouses who previously relied on a partner's withholding to cover joint tax liability may find themselves responsible for quarterly estimated payments as single filers.
Planning Through the Transition
The tax consequences of divorce are not fixed. Many of them can be anticipated, quantified, and — with proper planning — mitigated. The time to address them is during negotiation, not after the agreement is signed.
At RyanTax Pro, we assist individuals navigating life transitions with clear, personalized tax analysis. Understanding the full financial picture of a divorce settlement — including its multi-year tax implications — is one of the most valuable steps you can take before finalizing any agreement. The decisions made today will appear on your tax returns for years to come.